Table of contents
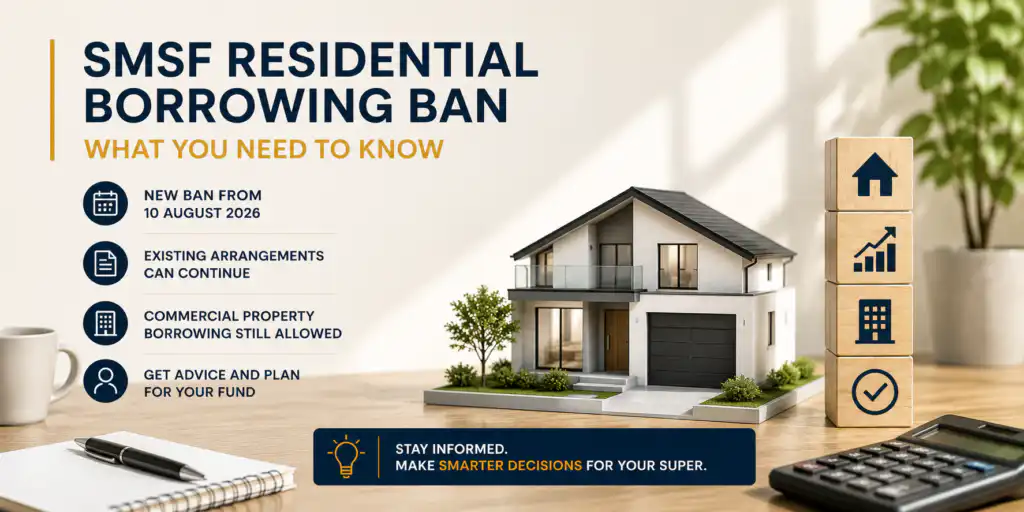
For any new arrangement, the answer is no. Since 10 August 2026, self-managed super funds have been unable to enter into a limited recourse borrowing arrangement (LRBA) to buy residential property. The change appears in Schedule 5 of the Treasury Laws Amendment (Tax Reform No. 1) Act 2026, which received Royal Assent on 26 June 2026 and took effect 45 days later. It applies from that point forward, so existing LRBAs can continue. SMSFs can also still borrow for commercial property where it meets the business real property tests.
What the ban actually does (and doesn't do)
Schedule 5 amended subsection 67A(2) of the Superannuation Industry (Supervision) Act 1993 by adding paragraph (c): where an LRBA asset is real property, it must be business real property within the meaning of section 66. Plain English version: residential property no longer qualifies for a new SMSF borrowing arrangement.
Whether the new restriction applies comes down to timing. The application rule covers arrangements entered into on or after 10 August 2026. Borrowings entered into before that date can still be maintained or refinanced. An acquisition may also proceed after commencement if it arises from an arrangement already entered into before the new rule began.
Treasury's 23 June 2026 release put the change in context. SMSF residential LRBAs make up less than 1 per cent of total residential property borrowing and less than half a per cent of new residential borrowing each year. Not a huge slice of the market, but a meaningful one for the trustees who use it.
| What changes | What stays the same |
|---|---|
| New LRBAs for residential property are prohibited | Existing residential LRBAs continue |
| Real property acquired under a new LRBA must be business real property | Commercial property LRBAs remain available |
| Applies to arrangements entered into on or after 10 August 2026 | SMSFs can still buy residential property outright with no borrowing |
| Bare trust structures now sit behind commercial deals, not new residential ones | Sole purpose test, in-house asset rules and investment strategy obligations are unchanged |
If you already have a residential LRBA
Nothing forces you to unwind it. The Treasurer confirmed on 23 June 2026 that existing arrangements stay in place, and the Act's application rule backs that up. Repayments continue on the terms you agreed with the lender. When you eventually sell, the usual CGT and loan-payout mechanics apply.
Refinancing a pre-commencement borrowing isn't caught by the ban either. The application rule specifically carves out maintaining or refinancing a borrowing under an arrangement entered into before 10 August 2026. That said, refinancing terms depend on what lenders will offer in the new landscape. Worth a conversation with both your lender and your accountant before you commit.
Compliance obligations haven't shifted. Funds with an existing arrangement still need to meet the same SMSF property rules they always did: sole purpose test, in-house asset limits, arm's length dealings, and trustee minutes that actually reflect the decisions made. The property has to fit the fund's investment strategy, and that strategy needs to be reviewed regularly. A strategy prepared years ago will not satisfy that obligation unless trustees continue reviewing it against the fund’s circumstances.
If you were mid-purchase on 10 August 2026
This is the least settled part of the change, and a blog can't answer it for your specific fund.
The Act's application rule says the ban does not apply where the asset acquisition happens under an arrangement entered into before commencement, even if settlement is after. At the 23 June press conference, the Treasurer also referenced a 45-day transition period for investments currently mid-stream. Between the two, there's a carve-out for genuine pre-commencement arrangements. What counts as an "arrangement entered into" is fact-specific.
In practice, the question turns on evidence. Was the contract of sale exchanged before 10 August 2026? Was the bare trust deed executed? Was the loan approved and documented? The more of those you can point to with dates before commencement, the stronger your position.
If this is you, gather the contract of sale, the SMSF bare trust deed, the loan approval, and every trustee resolution touching the purchase. Then book a free consult so someone can look at the actual documents. The fund’s position should be assessed from the dated documents rather than general commentary.
What you can still do if you want property exposure
Three paths remain open. Each has real trade-offs.
Buy residential outright, no borrowing. Legal, straightforward, and slow. The hurdle is balance. Most SMSFs don't hold enough cash to buy a metropolitan house or unit without gearing, and diversification matters once one asset dominates the fund.
Commercial property under the business real property tests. This is where borrowing still works. ATO ruling SMSFR 2009/1 sets out the two conditions: an eligible interest in real property, and use of the underlying land wholly and exclusively in one or more businesses. Section 66(6) also allows a primary production property to include a dwelling and private-use area up to 2 hectares, provided private use isn't the predominant use. The classic use case is a business owner leasing their premises back to their own operating company, all at arm's length.
Commercial LRBA with a bare trust. New LRBAs for business real property are still permitted, and the bare trust structure sits behind them the same way it always has.
| Situation | Available options |
|---|---|
| Want residential exposure, small balance | Not viable through the fund. Consider listed property (REITs) or hold outside super |
| Want residential exposure, large balance | Outright purchase, no borrowing |
| Business owner, own premises | Commercial LRBA on business real property, lease back at arm's length |
| Passive commercial investor | Commercial LRBA on qualifying business real property |
If you're weighing these up, our SMSF property team can walk through how funds structure compliant purchases under the new rules.
Beyond property
Property isn't the only asset class an SMSF can hold. Listed shares, ETFs, managed funds, cash and term deposits are all standard fare, alongside gold and other allowable assets. What ties it together is the investment strategy. It has to justify the mix, the diversification, and the liquidity of the fund. That's a core part of running an SMSF, and it's a trustee obligation, not a set-and-forget document.
How this fits with the rest of the tax package
The LRBA ban was one piece of a broader tax reform. A few knock-ons matter for SMSF trustees holding or considering property.
The 50 per cent CGT discount is scheduled to be removed for affected assets from 1 July 2027, replaced with cost base indexation. For SMSFs holding property, that changes the maths on eventual disposal. Model it before you assume the same net return you would've expected two years ago.
Negative gearing rules are being tightened for future investment properties, with existing arrangements preserved. Given the LRBA ban already stops new geared residential purchases inside super, the direct SMSF impact of the negative gearing change is limited. It still matters for personally held investment property.
A proposed minimum tax on some discretionary trust distributions from 1 July 2028 was announced as part of the same package but isn't yet law. Treat it as proposed, not legislated. Don't restructure family trusts on the strength of an announcement.
What trustees should do now
A practical list, in the order most trustees should tackle it.
1. Review the fund's investment strategy. If it still assumes a new residential LRBA is on the table, update it. Document the change with proper reasoning.
2. Update trustee minutes. Record that the strategy has been reviewed in light of the 10 August 2026 change and note the current position on property.
3. Check refinancing timing on any existing LRBA. If a refinance is on the horizon, plan it now rather than at the point of maturity. Talk to the lender early.
4. If you were mid-purchase, get advice on the transition carve-out. Gather the paperwork. Don't rely on general commentary.
5. Speak to your accountant well before 30 June. Funds that keep their records current give the accountant time to spot problems while they can still be dealt with. Leaving everything until May usually turns routine compliance work into an avoidable clean-up. A good SMSF accountant works from a rolling checklist, not a document request in May.
Frequently Asked Questions
Can my SMSF keep its existing loan?
Yes. The Act's application rule and the Treasurer's 23 June 2026 statement both confirm existing LRBAs are preserved. Repayments continue on the original terms.
Can my SMSF buy a house without borrowing?
Yes. The ban only affects borrowing. An SMSF can still buy residential property outright with fund cash, provided the purchase meets the sole purpose test, arm's length rules, and the fund's investment strategy.
Does the ban apply to commercial property?
No. Under amended section 67A(2)(c), LRBA real property must be business real property within the meaning of section 66. Commercial premises that meet the business real property tests in SMSFR 2009/1 are still eligible.
Can I refinance an existing SMSF loan?
Yes. The Schedule 5 application rule expressly excludes maintaining or refinancing a borrowing under an arrangement entered into before 10 August 2026. Availability still depends on what SMSF lenders will offer, and that guide is being updated for the new landscape.
What is business real property?
Per ATO ruling SMSFR 2009/1, business real property needs two things: an eligible interest in real property, and use of the underlying land wholly and exclusively in one or more businesses. A primary production property can include a dwelling of up to 2 hectares provided private use isn't predominant.
When did the ban start?
10 August 2026, 45 days after the Treasury Laws Amendment (Tax Reform No. 1) Act 2026 received Royal Assent on 26 June 2026.
Getting advice on your fund
This article is general information based on the Act as at Royal Assent and Treasury's public statements. It isn't personal advice, and it can't account for the specific facts of your fund. If you have an existing LRBA, were mid-purchase around commencement, or are weighing up commercial property, the sensible next step is a conversation with someone who administers these funds day to day. Our transparent SMSF pricing is published, and an initial consult is free.
References